Bank of Canada weighs a rate hike as household debt hits $2.64-trillion
The Bank of Canada will decide this Wednesday whether to hold its policy rate at 2.25 per cent or begin a series of increases, a choice that lands on households already carrying a record $2.64-trillion in consumer debt, according to a TransUnion report cited by columnist John Turley-Ewart.
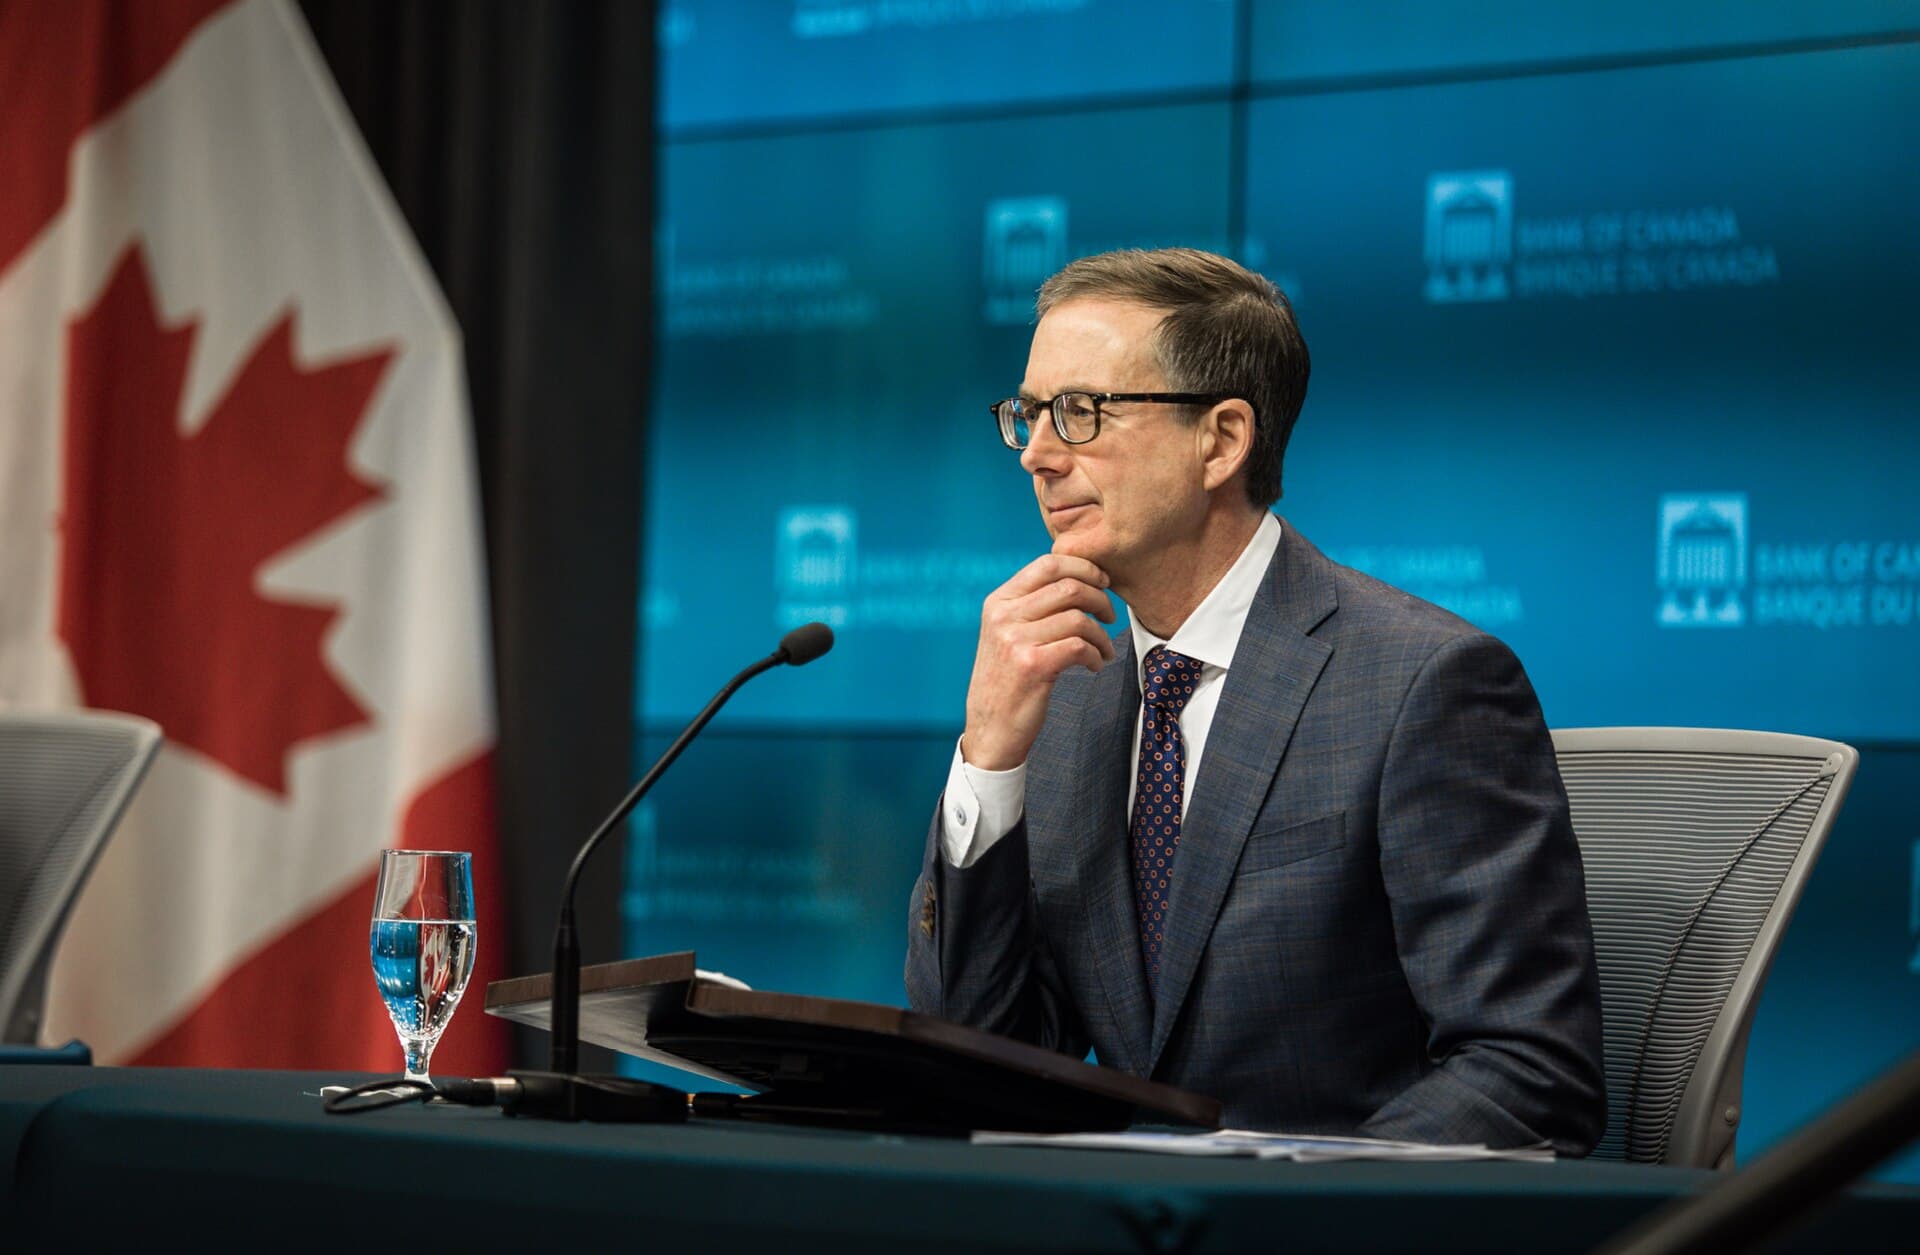
The case for holding rests on whether inflation, pushed to 3.1 per cent in September by energy prices, will fall back to the bank's 2 per cent target within six months to a year. Governor Tiff Macklem has framed the decision in those terms. Turley-Ewart argues that guessing at the path of energy prices in the current geopolitical climate amounts to economic astrology, pointing to reported drone activity on German soil and shifting Persian Gulf oil flows.
What is more predictable, he writes, is the domestic damage. Homeowners on variable-rate mortgages and home equity lines of credit will pay more interest, leaving less for everything else. Those renewing fixed-rate mortgages already face higher rates in anticipation of a move, first-time buyers will find qualifying harder, and sellers face downward pressure on prices. Builders have another reason to shelve projects, and businesses face higher borrowing costs they cannot easily pass on.
The backdrop is weak. Unemployment sits at 6.5 per cent nationally, and Statistics Canada reported the country lost 68,000 jobs in September after a decline of 42,000 the month before. Mortgage delinquencies are rising in Ontario, Prince Edward Island and British Columbia, and at least one Ontario insolvency firm is tracking the highest number of homeowner bankruptcies since 2016. Food Banks Canada counts 2.35 million visits a month, more than double the 2019 level, with almost 20 per cent of users holding jobs.
Turley-Ewart's question is whether chasing the 2 per cent target is worth it when the cost lands on household balance sheets and on the capacity to absorb what Prime Minister Mark Carney has called a trade war. If rates rise, he writes, it is mathematically certain that many Canadians will direct more income to interest payments and less to everything else.