Mapletree Pan Asia's DPU slips 3.5% as China reversions hit -29.9%
Mapletree Pan Asia Commercial Trust's distribution per unit fell 3.5% year on year to 1.94 cents in the quarter to September 30, as rental reversions in China stayed deeply negative and a previously disclosed tenant exit in Japan weighed on overseas income.
Gross revenue for the quarter was $207.5 million and net property income $153.5 million, down 5.0% and 6.3% respectively, the trust reported. For the first half, DPU fell 3.0% to 3.8 cents, with revenue of $413.9 million and net property income of $308.3 million, 5.3% and 6.5% lower. Finance expenses fell 14.4% over the half, limiting the damage to distributions.
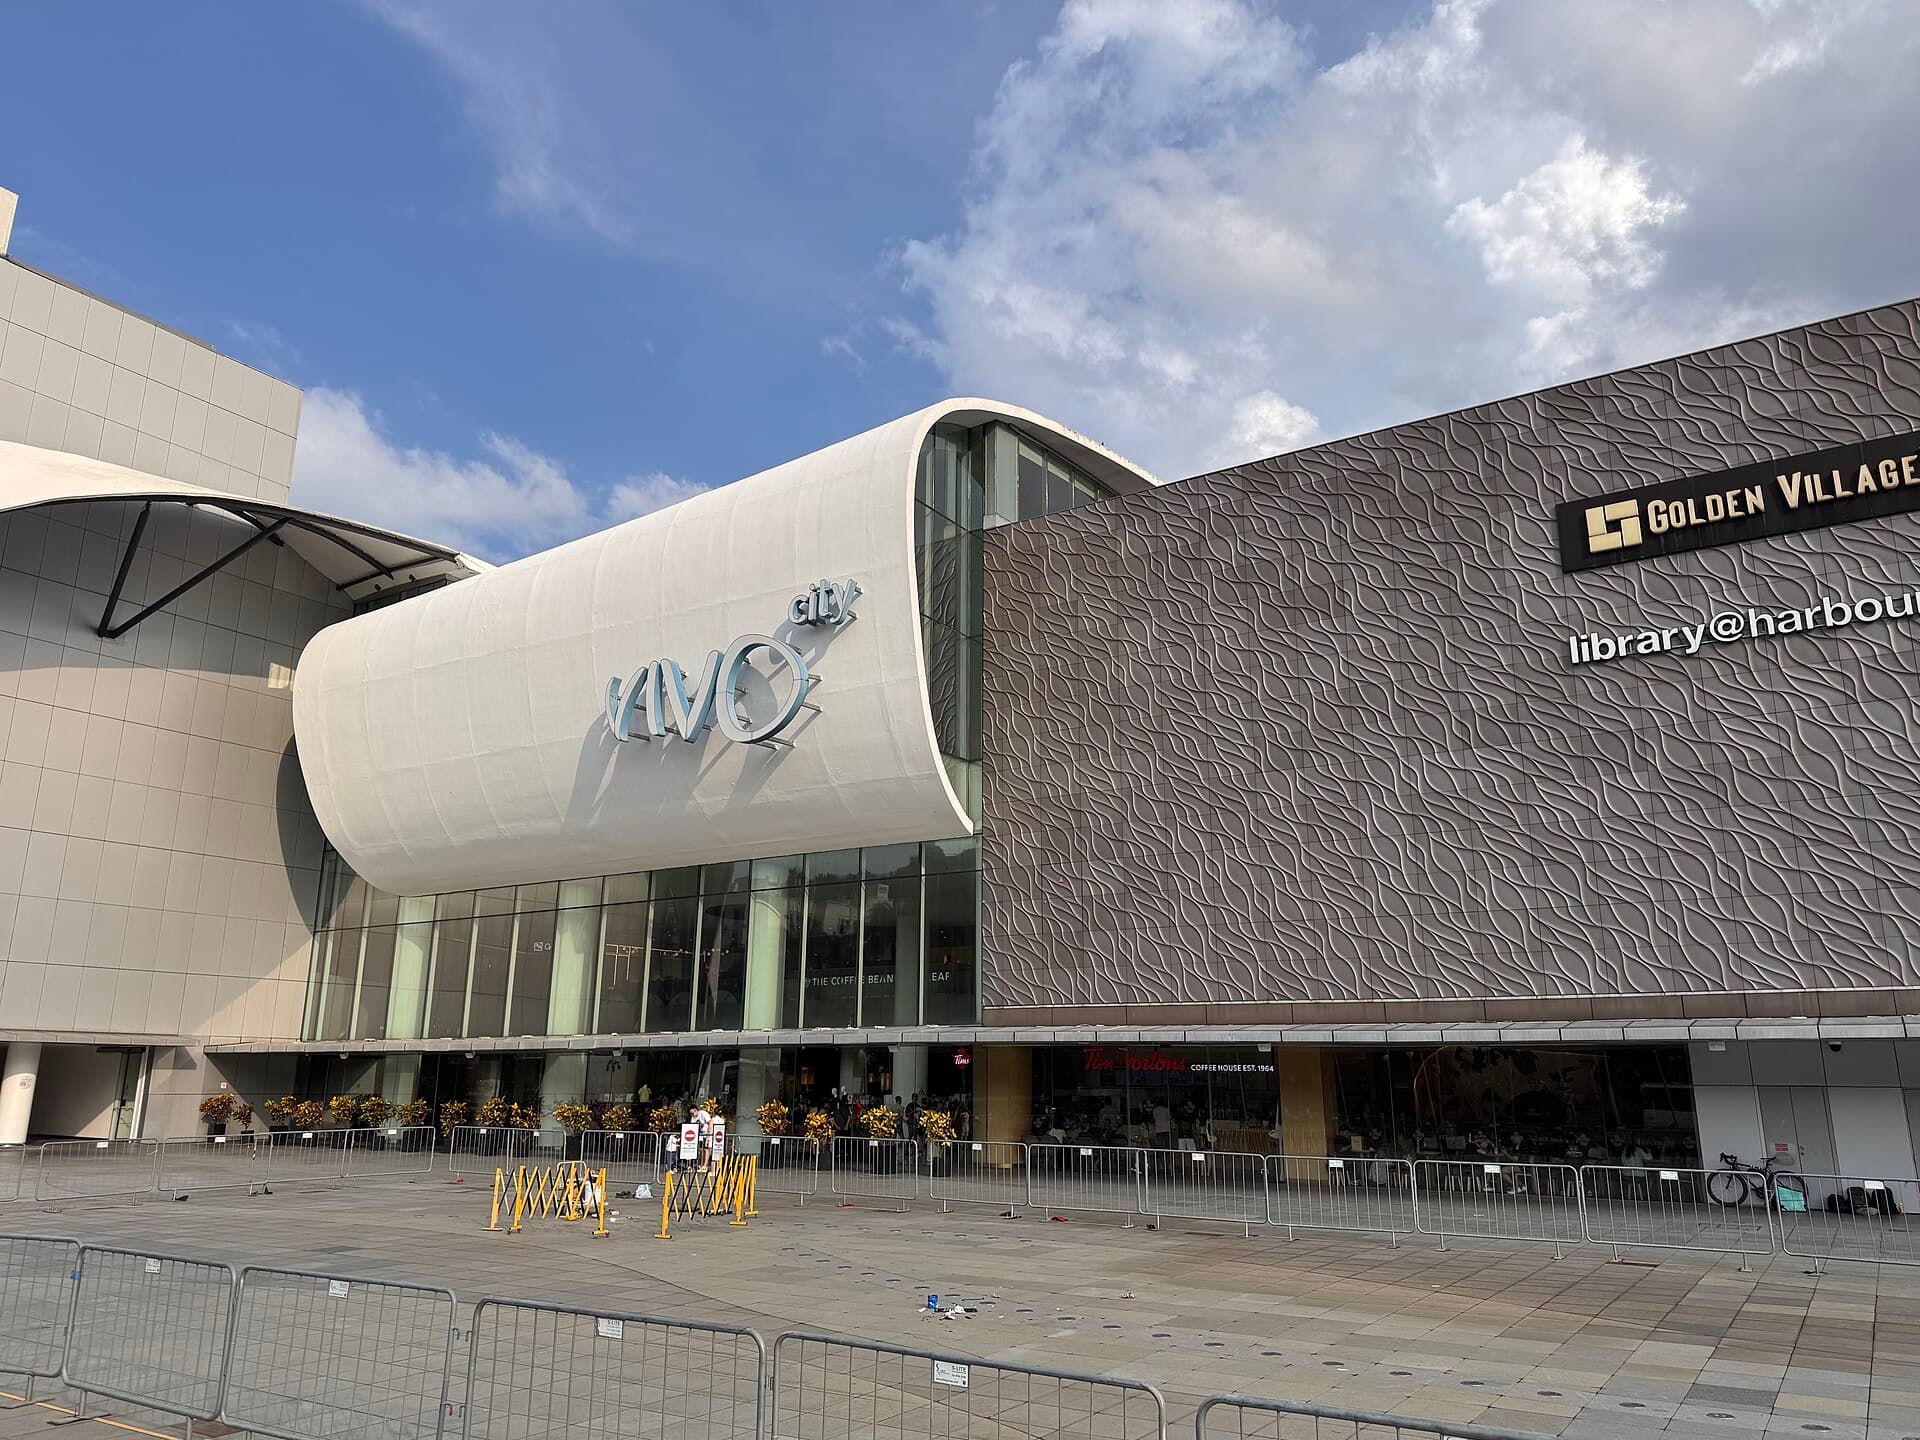
Singapore held the line. VivoCity, fresh from its Basement 2 asset enhancement, posted net property income growth of 5.0% for the quarter and 6.9% for the half, full committed occupancy and a 15% rental uplift, with tenant sales up 3.3% in the quarter. Mapletree Business City's committed occupancy rose to 95.4%, and key committed leases there are expected to start contributing rent progressively from the third quarter. Portfolio committed occupancy edged up 1.2 percentage points quarter on quarter to 85.6%.
The drag came from elsewhere. China's year-to-date rental reversion stood at -29.9%, with Festival Walk at -15.6% for the half, worse than the -9.1% recorded in the first quarter. Japan's committed occupancy was just 57.5%, reflecting the Fujitsu Makuhari Building non-renewal. The trust also had no contribution from assets divested in FY2025/2026, whose proceeds repaid debt, and a stronger Singapore dollar cut the value of yen and Hong Kong dollar income.
JP Morgan said it expects a negative market reaction but kept an Overweight rating with a June 2027 target price of $1.45. The broker flagged the positives as Mapletree Business City's occupancy climb, from 94.3% in the first quarter and 93% a year earlier, and VivoCity's continued strength. The trust's weighted average cost of debt edged up to 2.95% from 2.94%, and management said scope for further finance-cost savings has narrowed as rates rise; aggregate leverage rose to 38.1% from 37.7%.